Dubai real estate market report — Jan–Sep 2026
What actually happened in January–September 2026 — from 95,878 apartment sales registered with the Dubai Land Department, not from marketing decks: where prices stand after the February correction, which areas absorb the volume, and what the honest Q4 scenarios look like.
A correction with a running engine: volumes high, prices off the peak, a June–July rebound, a quieter August–September.
Sources: Dubai Land Department registered sales Jan–Sep 2026 (our own aggregation, ≥AED 100k, updated monthly); ValuStrat VPI July 2026; Reidin June 2026; Economy Middle East (July ready-home sales); Cushman & Wakefield Core; Khaleej Times.
- 95,878 apartment sales (AED 175.4B) + 9,481 villas (AED 37.5B) registered in Jan–Sep 2026
- Median apartment AED 1,225,000 · AED 1,712/sqft; median villa AED 3,250,000
- Prices −10% vs the Feb peak (ValuStrat) · +1.9% y/y (Reidin)
- 76% off-plan; off-plan premium +26%/sqft vs ready (AED 1,769 vs 1,400)
- Rents −6.7% Jan–Apr; June ready-home sales +46.8% m/m — strongest in 3 years
- Busiest areas: Dubai South 11,272 · JVC 7,171 · Dubailand Residence Complex 4,767
The headline numbers — from registrations, not listings
Everything below comes from individual sales registered with the DLD in Jan–Sep 2026 (residential, ≥AED 100k). Registered prices run below asking prices — this is what buyers actually paid:
| Segment | Sales Jan–Sep | Median price | AED/sqft | Off-plan |
|---|---|---|---|---|
| Apartments (citywide) | 95,878 | AED 1,225,000 | 1,712 | 76% |
| Villas & townhouses | 9,481 | AED 3,250,000 | 1,751 (plot) | 73% |
Top areas by transaction volume
| Area | Sales Jan–Sep | Median price | AED/sqft | Off-plan |
|---|---|---|---|---|
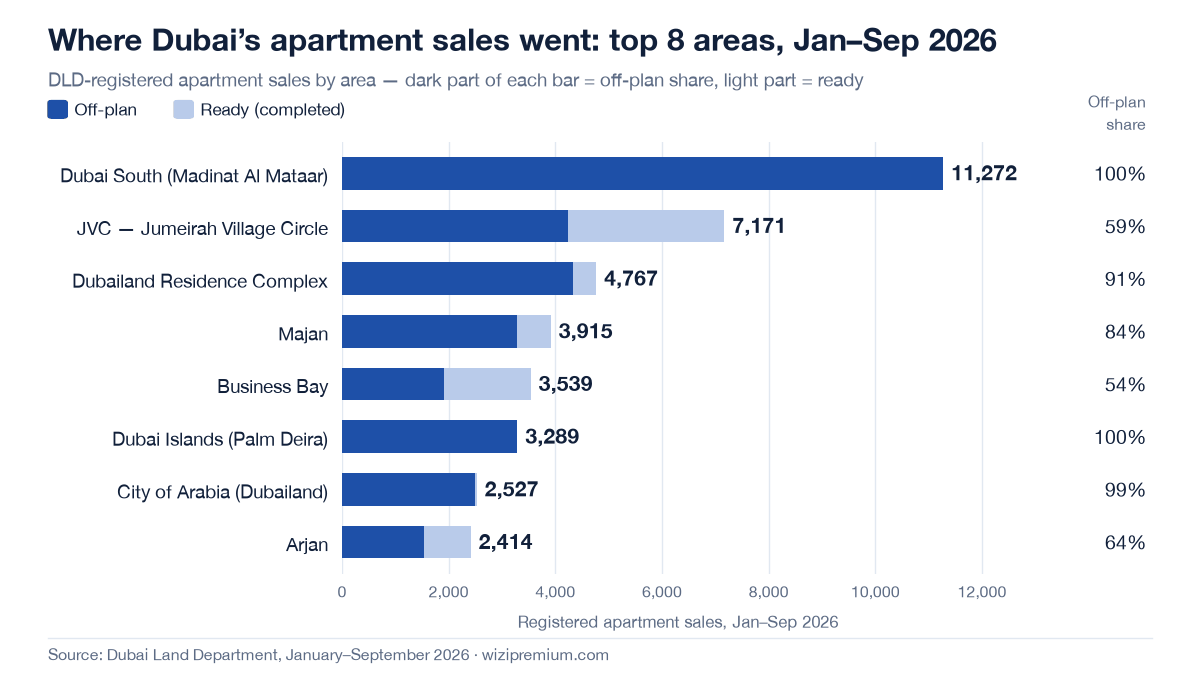
| Dubai South (Madinat Al Mataar) | 11,272 | AED 772,350 | 1,703 | 100% |
| JVC — Jumeirah Village Circle | 7,171 | AED 1,000,000 | 1,456 | 59% |
| Dubailand Residence Complex | 4,767 | AED 806,850 | 1,423 | 91% |
| Majan | 3,915 | AED 720,999 | 1,423 | 84% |
| Business Bay | 3,539 | AED 2,080,000 | 2,404 | 54% |
| Dubai Islands (Palm Deira) | 3,289 | AED 2,862,828 | 2,808 | 100% |
| City of Arabia (Dubailand) | 2,527 | AED 611,000 | 1,702 | 99% |
| Arjan | 2,414 | AED 939,755 | 1,587 | 64% |
Off-plan share = sales registered before completion. Dubai South (100%), Dubai Islands (100%) and City of Arabia (99%) are almost entirely off-plan, Dubailand Residence Complex is at 91% — that is where the new supply lands; Business Bay (54%) and JVC (59%) mix resale with launches.
What's holding up — and what's under pressure
Holding up
- Transaction volume: 95,878 apartment registrations in Jan–Sep — the market cleared roughly AED 20 billion of apartment sales a month through a correction
- Cash buyers fund >54% of deals — leverage stays low by design (central-bank LTV caps)
- Supply discipline: ~50k of ~120k planned 2026 units actually delivering (~40%)
- Prime: Knight Frank forecasts +3% for 2026 vs +1% market; 500 deals above $10M in 2025
- June ready-home sales +46.8% m/m — the strongest month in three years; July added another +11.4%
Under pressure
- Prices: ~10% below the February 2026 peak (ValuStrat VPI, −0.3% m/m in July after −1% in June — the slide is flattening)
- Rents: −6.7% Jan–Apr, worst in busy mid-market districts (JVC −10.3%, JBR −9.9%)
- Off-plan share at 76% of registrations — the market leans on developer payment plans
- UBS bubble score 1.09 («elevated», 5th globally) — external risk monitors are wary
- Fitch expects the correction to run deeper than its original −15% call
The war question: what the escalation actually did to the market
The February 28 escalation of the regional conflict is the single event that turned 2026 from a growth year into a correction year. The immediate hit was demand, not supply: UAE transactions fell ~37% year-on-year in early March as buyers paused, and ValuStrat's index started printing monthly declines from a peak it had reached just days earlier. Rents followed with a lag — down 6.7% between January and April, with the busiest mid-market rental districts (JVC, Arjan, Discovery Gardens, Sports City) seeing tenant leverage for the first time since 2020.
What the escalation did not do: trigger distressed selling or a credit event. Cash funds more than half of purchases, LTVs are capped, and January–September still closed with 95,878 registered apartment sales. June's +46.8% rebound in ready-home sales is the clearest signal in the dataset — when headlines calm, demand returns within weeks, concentrated first in completed stock rather than off-plan promises. That pattern (ready first, off-plan later) is the market telling you where the real floor is.
Q4 2026 outlook: the scenarios, not a crystal ball
The base case among rating agencies is a manageable correction. S&P's scenario ladder: 0…−5% if the region de-escalates, −10…−15% if the conflict grinds on, −20…−30% only under severe escalation — with apartments (≈385k units under construction to 2028) more exposed than villas. Fitch has already said the correction will run deeper than its first −15% estimate. Knight Frank's pipeline count to 2030 (~331k homes) means supply pressure is a 2027+ story, not a Q4 2026 one: this year's deliveries are running at ~40% of plan.
Our read for Q4: watch three dials. One — whether demand picks up again: after June's ready-home rebound (+46.8% m/m) apartment registrations held at 11,472 in July, then eased to 9,481 in August and 8,731 in September; a Q4 pick-up would confirm the floor is in. Two — the off-plan share: 76% over nine months (72% in September), and any wobble in developer payment-plan demand shows up there first. Three — rents: if the −6.7% slide steepens past −10% market-wide, yield math starts forcing asking prices down in the mid-market. For buyers this is a negotiation window — registered DLD medians, not asking prices, are the reference; this page updates monthly with the new registrations.
Common questions
How many property transactions were there in Dubai in Jan–Sep 2026?
The Dubai Land Department registered 95,878 apartment sales (AED 175.4B) and 9,481 villa/townhouse sales (AED 37.5B) between January and September 2026 — 105,359 residential deals worth about AED 212.8B combined. 76% of the apartment sales were off-plan. These are registrations of individual sales ≥AED 100k, not listings or press-release estimates.
Are Dubai property prices going up or down right now?
Both, depending on the yardstick — which is typical mid-correction. ValuStrat's valuation index sits ~10% below its late-February 2026 peak; the monthly slide eased to −0.3% in July after ~1% a month through spring; Reidin's transaction index shows +1.9% year-on-year. Registered medians (AED 1.23M apartments, AED 3.25M villas) are the hardest numbers in between.
How did the war affect Dubai real estate?
The February 28 escalation cut UAE transactions ~37% y/y in early March and started the price correction; rents fell 6.7% Jan–Apr. It did not trigger distressed selling: cash funds >54% of deals and June ready-home sales rebounded +46.8% m/m — the strongest month in three years. The market repriced and kept trading.
What is the forecast for Dubai property in Q4 2026?
Agency scenarios: S&P sees 0…−5% on de-escalation, −10…−15% if the conflict drags, −20…−30% only in a severe case; Fitch expects a deeper correction than its original −15%. Supply stays disciplined this year (~40% of plan delivering), so Q4 is a demand story — June's rebound suggests stabilisation in ready stock first.
Which Dubai areas sell the most property?
By Jan–Sep 2026 registrations: Dubai South / Madinat Al Mataar (11,272 apartment sales, 100% off-plan), JVC (7,171), Dubailand Residence Complex (4,767), Majan (3,915), Business Bay (3,539), Dubai Islands / Palm Deira (3,289) and City of Arabia (2,527). Affordable off-plan corridors dominate volume; Business Bay is the busiest mixed resale market.
Where does this report's data come from?
From sales registered with the Dubai Land Department (residential, ≥AED 100k, January–September 2026), aggregated by us and refreshed monthly — the same dataset behind our price index. Registered prices are what buyers actually paid, typically below asking prices on portals. August was recounted to include late registrations from 31 August; September may still be revised slightly.
The data pages behind this report
Get a shortlist priced against DLD data
Tell us your budget and target area — we'll send options priced against the registered DLD median for their buildings, so you see exactly what is above and below the real market. WIZI PREMIUM — Property Finder Awards 2025 winner (Quality Brokerage, Dubai Boutique).